This article is for informational purposes only and is not financial advice. TheGatBull may earn a commission from some links at no cost to you — see our disclosure and full disclaimer.
Not financial advice. This article is informational and is not a recommendation to buy or sell any security.
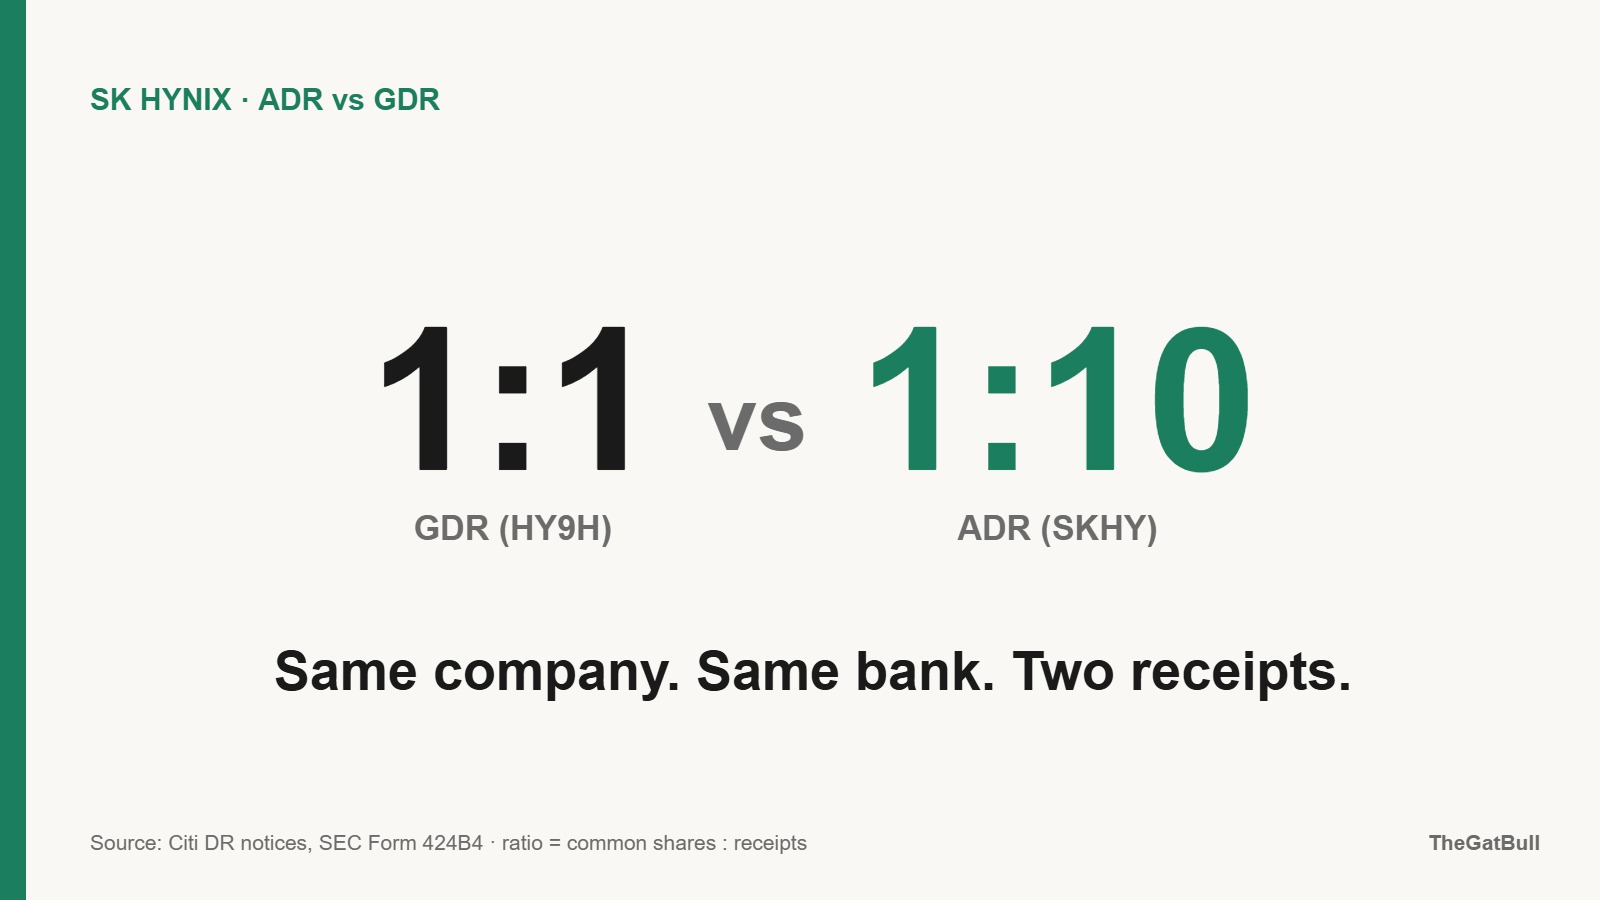
Take one share’s worth of an SK Hynix dividend. On the company’s GDR — listed in Luxembourg and traded in Germany as HY9H — the depositary’s fee is $0.02. The Nasdaq ADR (SKHY) splits that same share into ten ADSs (American depositary shares, the units SKHY trades in), so under the contract’s cap the fee on that one share can reach $0.50.
The same bank, Citibank, runs both receipts. The difference comes mostly from the ratio, not the bank — and the GDR is not something most US individual investors can buy (see §1-B).
What this means if you hold EWY: the fund holds Seoul common shares directly, so it pays neither the GDR nor the ADR depositary fee (SK Hynix was 23.72% of EWY as of September 30, per iShares). It carries a 0.59% annual expense ratio on assets instead — compared in §6 below.
On August 7, 2026, SK Hynix declared a quarterly dividend of ₩375 a share. A holder of the common shares in Seoul receives ₩375.
What does a holder of SKHY on Nasdaq receive?
Answering that means looking in three places: the filing in Seoul, the securities depository in Busan, and a contract signed in New York.
1. The arithmetic
One common share = ten ADSs. So the amount attaching to a single ADS is ₩37.5.
At the 15:30 Seoul FX close of ₩1,416.1 on August 7, that is $0.0265.
Korean withholding tax comes out of it. Under the US–Korea tax treaty the rate on portfolio dividends is 15%.
In Korea, though, 15% is not automatic. The base rate is 22% (20% national plus a 10% local surtax), and the treaty 15% applies only if a certificate of residency and a reduced-rate application are on file with the withholding agent before payment. Without the paperwork, 22% applies. That chain is taken apart in Korea’s dividend tax cut and what it means for foreign investors.
For ADRs the depositary handles this in bulk, so 15% is the usual assumption — but it is worth checking on your own account. The math below uses 15%. At 22% the post-tax figure falls to $0.0207.
That leaves $0.0225. Then comes the part that matters.
SK Hynix’s prospectus filed with the SEC, page 145, “Fees and Charges,” third row:
Distribution of cash dividends or other cash distributions — Up to US$5.00 per 100 ADSs (or fraction thereof) held
$5.00 per hundred is $0.05 per ADS.
Dividend per ADS            $0.0265
Korean withholding, 15%     −$0.0040
                          ──────────
Post-tax                     $0.0225

Distribution fee cap        −$0.0500
                          ──────────
  Gap                        $0.0275   ← how far the cap sits above the dividend
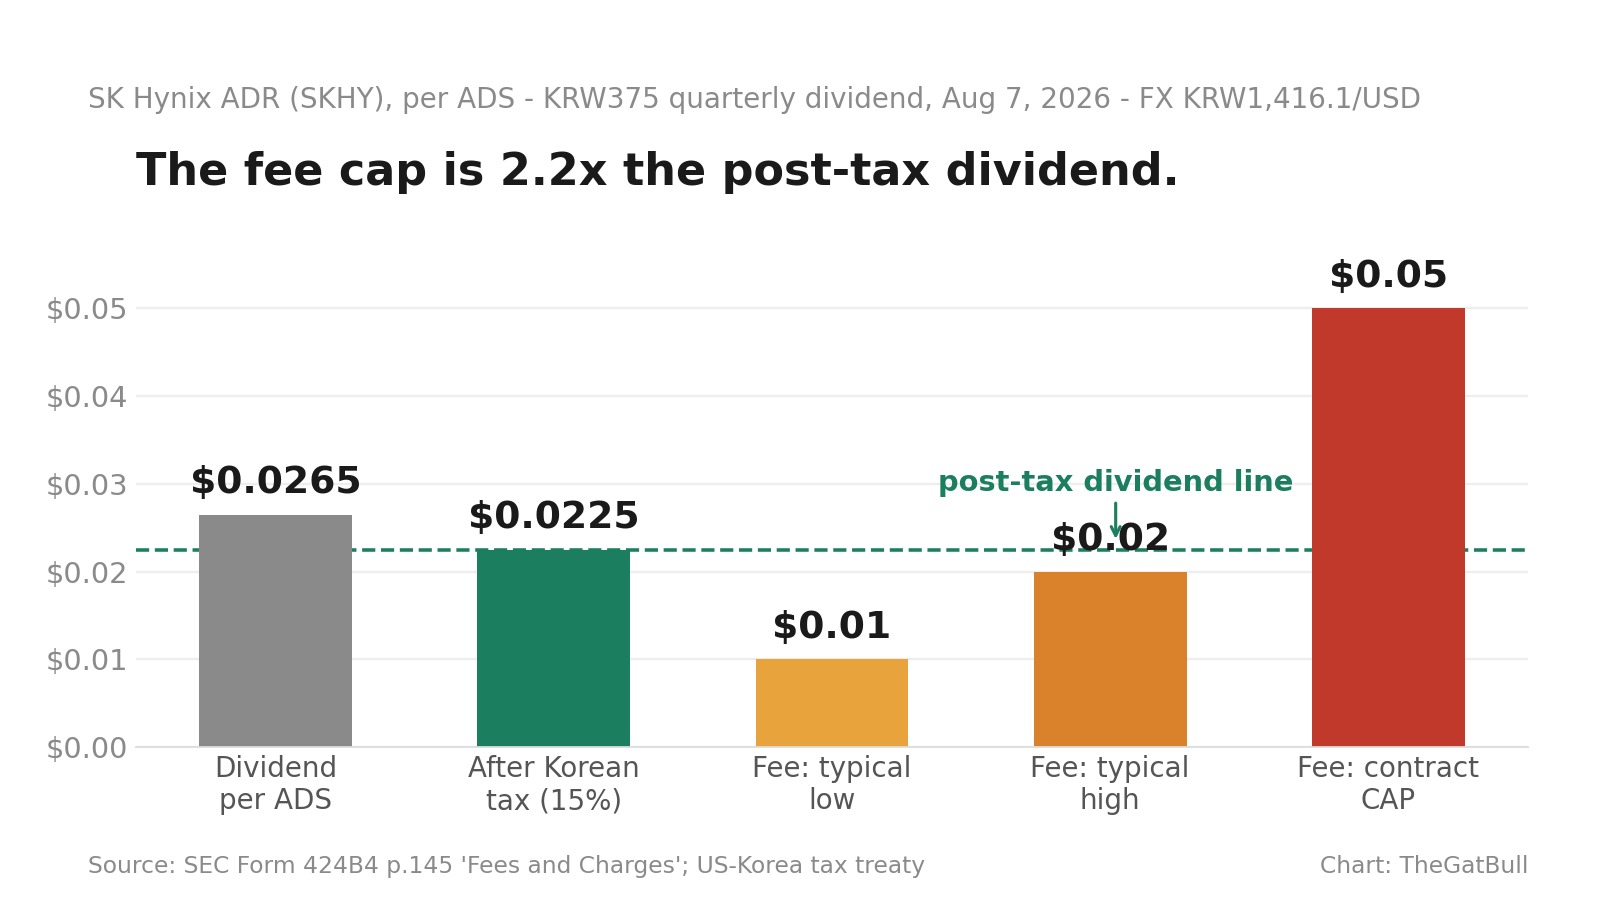
The cap the contract allows is about 2.2 times the post-tax dividend.
Does money leave my account if the fee is larger?
This is the most important question in this article, and I cannot answer it definitively. So here is what is known and what is not.
- Known: Section 4.1 of the deposit agreement says only that the depositary distributes the amount received net of fees and withheld taxes. Whether a deduction can exceed the distribution itself is not addressed.
- Known: In the industry, when a distribution is small or absent, depositary fees are sometimes billed through DTC to the broker, who then debits the customer’s account (⚠️ general industry practice — not confirmed for SKHY).
- Unknown: How this is actually handled for SKHY.
→ This article floors the net at $0 and does not compute a negative. But “it stops at zero” is not guaranteed. There is one way to find out: ask your broker how ADR fees are charged. A past ADR dividend statement usually shows it.
And tax and fees are not the same kind of deduction. The $0.0040 of Korean withholding can generally be recovered in a taxable account through the US foreign tax credit (Form 1116). The $0.05 fee comes back through no channel at all.
1-B. SK Hynix’s other receipt: the GDR (HY9H)
What is HY9H?
It is SK Hynix’s global depositary receipt (GDR). The primary listing is on the Luxembourg Stock Exchange (ticker HYXS LX); HY9H is the symbol the same receipt (ISIN US78392B1070) uses on German exchanges, where it is listed as “SK HYNIX GDR 144A/REGS 1”.
When was it created?
In June 2006, then-Hynix Semiconductor and selling shareholders issued $747 million of GDRs, sold under the US private-placement rule (Rule 144A) and the offshore rule (Regulation S) and listed on Luxembourg’s Euro MTF (per a notice from Cleary Gottlieb, the law firm on the deal — firm-reported).
What is the ratio?
One GDR = one common share. Three notices from the depositary, Citibank, all state “ORD:DR 1:1”. That is the opposite direction from the ADR, where one share = ten ADSs.
What does it charge on dividends?
$0.02 per GDR per dividend. In the dividend history Citi publishes, every distribution since 2014 carries the same amount (confirmed from the depositary’s own notices). If Korean withholding is reduced to the treaty rate, a $0.0075 per GDR processing fee is added.
Separately, an annual service fee of $0.02 per GDR, unrelated to dividends, has been charged once a year (on a March record date) at the same amount since 2010.
What did one actual payment look like? The 2025 year-end dividend (₩1,875, per Citi’s April 24, 2026 notice)
| Item | Per GDR |
|---|---|
| Gross dividend (at the depositary’s conversion rate of ₩1,484.61) | $1.2630 |
| Dividend fee + reduced-rate processing fee | −$0.0275 |
| Net, 0% withholding bracket | $1.2355 |
| Net, 22% withholding bracket | $0.9651 |
The fees come to about 2.2% of the gross. The 22% net matches $1.2630 × 0.78 − $0.02 exactly, which suggests the processing fee is not charged when no reduced rate is claimed (our arithmetic on Citi’s figures — an observation, not a confirmed rule).
Note: ₩1,484.61 is the depositary’s conversion rate, not the 15:30 Seoul FX close.
Is the record date the same as Seoul’s?
Not always. For this payment the record date for the common shares was February 28, 2026, and for the GDR February 27 — one day apart. Payment came on April 24 for the common shares and May 1 for the GDR, a week later. It is an example of what §4 describes: the depositary sets its own record date. For the August 31 payment, by contrast, Citi announced a GDR record date identical to the common-share date.
Same dividend, two receipts — one share’s worth, side by side
| One common share’s worth | GDR | ADR (SKHY) |
|---|---|---|
| Number of receipts | 1 | 10 |
| Fee per dividend | $0.02 (actually charged) | Up to $0.50 (10 × $0.05 cap) |
| Annual service fee | $0.02 (actually charged) | Up to $0.50 (assuming one record date) |
| Strength of confirmation | confirmed from Citi notices | contract cap — actual charge not confirmed |
At the cap, that is 25 times as much. Even if the cap is not fully used, the conclusion is hard to flip: for the ADR to match the GDR, its rate would have to fall to $0.002 (0.2 cents) per ADS.
On the ₩375 quarterly payment: the GDR takes $0.02 out of about $0.2648 gross per share (about 7.6%), while the ADR’s cap allows $0.05 against $0.0265 gross per ADS (about 189%) — at the August 7 Seoul 15:30 FX rate of ₩1,416.1, before tax (illustrative: the Seoul rate, not the depositary’s conversion rate).
Under the Gat. Two receipts, one bank. The same Citibank processes the same company’s same dividend twice — one contract takes two cents a share, the other is written to allow up to fifty cents. The bank is not being greedy. The fee is a flat amount per receipt, and the ADR cut one share into ten receipts — with a higher per-receipt cap ($0.05 against $0.02) on top. View, not advice.
So can a US investor just buy the GDR?
Not simply. The “144A” in its name means it was sold under the US private-placement rule, which generally limits resale inside the US to qualified institutional buyers (QIBs). This is a general rule, not confirmed from an SK Hynix document. For Samsung Electronics’ GDR, which has the same structure, Samsung’s investor-relations page states directly that US residents may not trade it.
And, per Citi’s June 29, 2026 notice, no new GDRs are being created. Citi closed its books for new GDR issuance from the close of business on July 2, 2026. The stated reason, verbatim: “establishment of the Company’s ADR Facility and its upcoming ADR Offering”. The reopening date is listed as “TBD”.
→ The routes that actually reach SK Hynix from a US account — the ADR, EWY, or Seoul shares directly — are laid out in How to Buy SK Hynix Stock From the US.
What happens to the ADR and GDR in a stock split?
First: no split has been decided (as far as we could confirm, as of October 5, 2026). SK Group chairman Chey Tae-won said in New York on July 11 that a split would naturally follow if requests for one grew, adding that there was no formal proposal from the CFO yet (press-reported, Edaily).
If one comes: section 1.32 of the ADR deposit agreement provides that, on a split-up, “shares” means the successor securities that result, and section 1.4 says the ADS-to-share ratio is subject to amendment, “which may give rise to Depositary fees” (the deposit agreement filed with the SEC — primary). In other words, a split cannot be assumed to be a free event for ADR holders. The GDR’s deposit agreement does not appear to have been filed with the SEC, and we could not find the original — how the GDR would handle a split is not confirmed.
2. First, honestly — “Up to” is a cap
Do not read that number as “the fee eats the dividend.”
Up to is a contractual ceiling, and the depositary charges within it. Industry practice commonly runs $0.01–$0.02 per distribution (⚠️ a general industry range; the actual SKHY charge has not been published).
So here are three cases side by side.
| Charge | Share of post-tax dividend | Net per ADS |
|---|---|---|
| Contract cap, $0.05 | 222% | nothing left |
| $0.02 | 89% | $0.0025 |
| $0.01 | 44% | $0.0125 |
The spread across those rows is fivefold. At 44% more than half the dividend survives; at 222% none does. Which row applies is settled by the depositary’s notice — the range is as far as this article can go.
Now look at what the denominator actually is
Everything above is percentages. The dollar figures tell a different story.
Take 1,000 ADSs — roughly a $100,000 position (converting the August 7 Seoul close).
| This quarter | Annual | |
|---|---|---|
| Dividend, post-tax | about $22.50 | about $90 |
| Fees | $10 – $50 | $40 – $250 |
A hundred thousand dollars produces ninety dollars of dividends a year. The fee may be less than that, or more than double.
So the 222% in this article has a denominator of $22.50. The ratio is correct — but it is large because the dividend is nearly nothing, not because the fee is large.
Better to know that before reading on.
3. Why it works out this way: the ratio decided it
The fee is a flat amount per ADS. It does not scale with the dividend.
SK Hynix’s ratio is 1 share = 10 ADSs. The dividend gets cut into ten pieces.
Had the ratio been 1:1, the dividend would be $0.265, post-tax $0.225, and the same $0.05 fee would have come to 22% of it. Exactly one tenth of 222% — because the ratio was ten times.
Under the Gat. An ADR ratio is set at listing. It is a technical choice about putting the share price in a range American investors find familiar, and it is generally not made with dividends in mind. Yet that one decision determined the economics of this dividend. The ratio divides the share price, and it divides the dividend with it. The fee does not divide. View, not advice.
For a comparison anchor, TSMC (NYSE: TSM) runs at 1 ADS = 5 common shares as generally reported (⚠️ not verified against a primary source) — the opposite direction, so more dividend rides on each ADS and a flat fee weighs proportionally less.
Not a perfect parallel — Taiwan and Korea differ in withholding rates and in depositary terms. Only the structure is shared: the ratio governs the economics of the dividend.
How the listing itself was structured is taken apart in the SKHY IPO prospectus breakdown.
4. Three more things, beyond the fee
The same page 145 lists further charges borne by ADS holders.
One. The FX spread.
“the fees, expenses, spreads, taxes and other charges of the depositary and/or service providers … in the conversion of foreign currency”
Section 4.8 of the deposit agreement goes further: the depositary and its affiliates may act as principal in that conversion. Trading for their own account. You choose neither the rate nor the timing.
Two. The record date may not be the same one.
Under section 4.9 the depositary fixes its own ADS record date. The wording: it shall make reasonable efforts to set it “as closely as practicable” to the record date set in Korea.
“Efforts” is not “the same.” Holding SKHY on August 31 did not by itself settle whether you would receive that dividend.
The GDR shows how this plays out: SK Hynix’s GDR used a record date one day earlier than the common shares for the 2025 year-end dividend (see §1-B).
Three. There is a separate service fee.
The “ADS Services” row is capped at US$5.00 per 100 ADSs ($0.05 per ADS), charged on record dates the depositary establishes, independent of any dividend.
⚠️ How often it is charged is not stated in the contract. The text says only “held on the applicable record date(s) established by the depositary” — plural. The annual figures below assume once a year; more record dates means more.
On an annual basis: the fixed dividend of ₩1,500 is ₩150 per ADS, $0.106, post-tax $0.090. The fee ceiling is four distributions at $0.05 plus one service charge — $0.25. That is 2.8 times.
5. What kind of structure is this
Page 138 of the prospectus sets it out precisely.
- The shares sit in Busan. The custodian is the Korea Securities Depository, at 40 Munhyeongeumyung-ro, Nam-gu, Busan
- The depositary sits in New York. Citibank, N.A., 388 Greenwich Street
- You are a party to a contract. The original: “If you become an owner of ADSs, you will become a party to the deposit agreement“
And then one decisive line.
“The deposit agreement and the ADRs are governed by New York law. However, our obligations to the holders of common shares will continue to be governed by the laws of Korea.”
Your rights run on New York law. The company’s obligations run on Korean law.
That is why there can be two record dates. A Korean company fixes one under Korean law; a New York depositary fixes its own under a New York contract. Two legal systems process a single dividend twice.
Under the Gat. Buying an ADR is not buying a share. It is entering a contract with a bank that holds the share for you. The contract is public at the SEC and the fee schedule is on page 145. Almost nobody reads it before buying — I hadn’t either, until this week. Reading it changes what you think you are holding, slightly. View, not advice.
6. If you hold EWY instead
You do not pay the ADR depositary fee. The iShares MSCI South Korea ETF holds Seoul common shares directly, so the ADR structure never enters.
You do still pay Korean withholding tax — it is handled at the fund level. So this is not sidestepped wholesale; what is sidestepped is one line item, the depositary fee.
Something else attaches instead: an expense ratio taken daily from net assets, and a distribution schedule that does not match the company’s. You will not see when SK Hynix’s dividend arrived, or how much of it did.
Measured against the same denominator, the picture flips
ADR fees are flat per event; ETF fees are proportional to your balance. Use the dividend as the denominator and the first looks large. Use assets as the denominator and the second does.
Per year, against an ADS worth roughly $100:
| Annual cost | |
|---|---|
| ADR — one service record date, cap fully used ($0.25) | 0.25% |
| ADR — industry-typical (4 × $0.02 + $0.02 service = $0.10) | 0.10% |
| EWY expense ratio | 0.59% |
⚠️ Those ADR figures are not ceilings. As noted in §4, the contract does not state how often the service fee is charged. Quarterly record dates would make it $0.40 a year — a 0.40% cost ratio. Still below EWY.
⚠️ The $0.02 service-fee assumption has no source in this article. Only the $0.01–$0.02 per-distribution range is generally reported; a typical service-fee figure could not be confirmed.
Which denominator is right depends on why you hold the stock. If it is for income, the first. If it is for the share price, the second.
(The $100 per ADS converts the August 7 Seoul close. The actual market price carries a premium and is higher, which pushes the cost ratio lower still.)
Where SK Hynix sits inside EWY is laid out in the EWY concentration piece; the standing page for this stock’s dates, ratios and status is the SK Hynix investor hub. How far the ADR price runs from the Seoul price is in the ADR premium versus Seoul shares — the premium is a far larger variable than any fee here.
7. So what do you actually do
One. Confirm how your broker charges ADR fees. As §1 noted, what happens when the fee exceeds the dividend is set by your broker, not the deposit agreement. A past ADR dividend statement usually shows it.
Two. Don’t reuse the Seoul dates. For the August payment the Korean record date was Monday, August 31, and with Seoul’s T+2 settlement the last day to buy the common shares was Thursday, August 27. But ADRs follow the ADS record date and ex-date the depositary sets. For the next payment too, check the depositary notice — do not simply use the Seoul dates.
Three. Look at the number as it is. Against the August 7 close of ₩1.42m, ₩375 a quarter is 0.026%, or 0.11% annualised. The company did not design the dividend as an income stream — the fixed payout is a floor, and the variable part arrives as special dividends and buybacks. That is how the 2025 total reached ₩3,000.
Four. The third-quarter package came as a buyback, not a dividend. The additional shareholder return was announced on August 19: a ₩40tn share buyback, with all of the repurchased shares to be cancelled. Because it was a cancellation rather than a dividend increase, the flat-fee arithmetic in this article still stands. Who benefits is worked through in who gains from SK Hynix’s ₩40tn buyback.
So which is it — the conclusion
Two things have been said here: that the fee can exceed the post-tax dividend, and that measured against assets it is cheaper than EWY. Both are true, which can leave the answer blurred. So, plainly:
One. This fee is not a reason to buy or sell SKHY.
On a $100,000 position that is $40–$250 a year across the range in §2 (from industry-typical rates up to the contract cap; the actual SKHY charge is not confirmed). For scale, SK Hynix’s Seoul common shares moved −35% over July 2026 and +29.95% on July 31 alone (KRX closes — the +29.95% stopped at Korea’s ±30% daily price limit for individual stocks; the Nasdaq ADR has no such limit). Next to moves like that, the fee is small — not zero, but unless you bought it for the dividend, not large enough to change the decision.
Two. If income is the point, this is not the stock.
0.026% a quarter, 0.11% a year. After tax and fees, effectively nothing survives. The company did not build it as an income stock.
Three. The small-dividend structure is still visible.
Q3 brought a share buyback for cancellation rather than a bigger dividend. The dividend stayed small, so a flat fee on a small dividend remains the structure you can see.
Four. And there is one thing to check. Whether money leaves your account when the fee exceeds the dividend — that is decided by your broker, not the deposit agreement. One look at a past ADR dividend statement answers it.
Reading Korea through this one stock
Korea has spent two years pushing companies to return more to shareholders. SK Hynix raised its fixed annual dividend from ₩1,200 to ₩1,500, and in 2025 added a special dividend to reach ₩3,000.
But how much of that money survives the trip to a US account is not decided by Korean policy. It is decided by a deposit agreement signed in New York — one written in flat fees that do not scale with the dividend, filed publicly at the SEC, and read by almost nobody.
The more Korea’s value-up push succeeds, the less this structure matters. The less it succeeds — or the smaller the dividend — the more this structure outweighs the dividend itself.
The August payment is the second case. Which is exactly why it is visible now.
One more thing. For a long time a common door Korean large caps used to reach overseas investors was the institutional GDR — in SK Hynix’s case cheap, but largely closed to US individuals. SK Hynix shut new issuance through that door and opened a retail ADR. Access widened, and the trade-off was a flat per-receipt fee (capped, not confirmed as charged) now applied to a share cut into ten receipts. If other Korean large caps follow the same road to Nasdaq, the ratio they choose may matter to dividend investors as much as the listing itself.
Not financial advice — a view from Seoul, not a recommendation to buy or sell. Fees, tax rates and record dates vary with the depositary’s notices and your own tax situation.
Sources
- SEC — SK hynix Inc., Form 424B4 (prospectus) — page 138 depositary structure, page 145 “Fees and Charges” (primary)
- SEC — Deposit Agreement with Citibank, N.A. — §4.1 cash distributions, §4.8 currency conversion, §4.9 ADS record date, §1.4 ADS ratio amendment, §1.32 split-up (primary)
- Citi — appointment as depositary bank for SK hynix, July 16, 2026 (primary)
- Citi Depositary Receipt Services — SK hynix Inc. GDR (CUSIP 78392B107): dividend history; dividend notices of April 24, 2026 and August 7, 2026; depositary service fee notice of January 5, 2026 and fee history; book-closure notice of June 29, 2026 (primary)
- Deutsche Börse · Börse Stuttgart — “SK HYNIX GDR 144A/REGS 1” (ISIN US78392B1070, WKN A1JWRE) listing pages (primary — security identification)
- Cleary Gottlieb — Hynix Semiconductor $747 million GDR offering, 2006 (firm-reported)
- Samsung Electronics investor relations — GDR information (primary; US-resident trading restriction)
- iShares — EWY holdings as of September 30, 2026 (primary)
- Edaily, July 11, 2026 — Chey Tae-won on a possible stock split (press-reported)
- Korea Securities Depository — custodian
- Financial Supervisory Service DART — SK Hynix cash dividend resolution, August 7, 2026 (reported by five Korean outlets; the filing text was not read directly)
- PwC — Korea corporate withholding taxes · IRS — US–Korea income tax convention
- Financial News, SBS Biz, EBN, Insight Korea and Singlelist, August 7, 2026 — dividend declaration (five outlets in agreement)
Not financial advice. TheGatBull does not recommend buying or selling any security. All figures are stated as of the basis dates given; investment decisions and their consequences are your own.
Frequently Asked Questions
How much is the SK Hynix ADR dividend per ADS?
One common share equals ten ADSs, so the ₩375 declared on August 7, 2026 works out to ₩37.5 per ADS — about $0.0265 at the August 7 Seoul FX close. Korean withholding tax and the depositary’s fee come out of that.
What is the depositary fee on the SKHY ADR?
The deposit agreement caps the cash-distribution fee at US$5.00 per 100 ADSs, which is $0.05 per ADS. That is a cap, not the amount actually charged — the depositary sets the charge within it. A separate ADS Services fee is capped at the same rate per record date.
Will the fee wipe out the dividend?
It depends on what is actually charged. Against a post-tax dividend of $0.0225 per ADS, the $0.05 cap is 222%. Rates commonly seen in the industry, $0.01 to $0.02, would take 44% to 89%. The real figure comes from the depositary’s notice. In dollar terms, a 1,000-ADS position sees about $22.50 after tax this quarter.
Does holding SKHY on the Korean record date guarantee the dividend?
Not necessarily. For the August payment the Korean record date for the common shares was August 31. Under section 4.9 of the deposit agreement the depositary sets its own ADS record date, undertaking only to fix it “as closely as practicable” to the Korean one. Check the depositary’s notice for the ADS record date and ex-date.
Does holding EWY avoid these fees?
It avoids the ADR depositary fee, because the fund holds Seoul common shares directly. It does not avoid Korean withholding tax, which is handled at the fund level. In exchange you pay a 0.59% annual expense ratio on assets rather than a flat fee per distribution.
Has SK Hynix always paid dividends?
Yes. It has paid quarterly dividends since 2022, and its 2025 total was ₩3,000 per share, a record. The 2025–2027 shareholder-return policy sets a fixed annual dividend of ₩1,500, which is the ₩375 a quarter declared on August 7.
What is SK Hynix GDR HY9H?
HY9H is the symbol SK Hynix’s global depositary receipt uses on German exchanges. Its primary listing is in Luxembourg (HYXS); one GDR equals one common share, and the depositary is Citibank. It was issued in 2006 under Rule 144A and Regulation S, and is generally not available to US individual investors (see §1-B).
What fee does the SK Hynix GDR charge on dividends?
$0.02 per GDR per dividend, unchanged since 2014, plus a $0.0075 processing fee when the treaty withholding rate is claimed, and a separate annual service fee of $0.02 — per Citi’s notices.
Will an SK Hynix stock split change the ADR or GDR?
As far as we could confirm, no split had been decided as of October 5, 2026. The ADR deposit agreement allows the ADS ratio to be amended and says that may give rise to depositary fees. How the GDR would be handled could not be confirmed from a public original.
This article is for informational purposes only and is not financial advice. TheGatBull may earn a commission from some links at no cost to you — see our disclosure and full disclaimer.
 Written by Mr.Gat — TheGatBull
Korean market coverage from a Seoul-metro-based operator who reads the filings in the original language. Every price on this site is the KRX regular-session close (15:30 Seoul); every figure states whether it came from a primary filing, the press, or our own calculation. Drafts are AI-assisted, then verified against the original Korean documents and edited by a human before publishing.
Found an error? Tell us — corrections get priority. How we work →