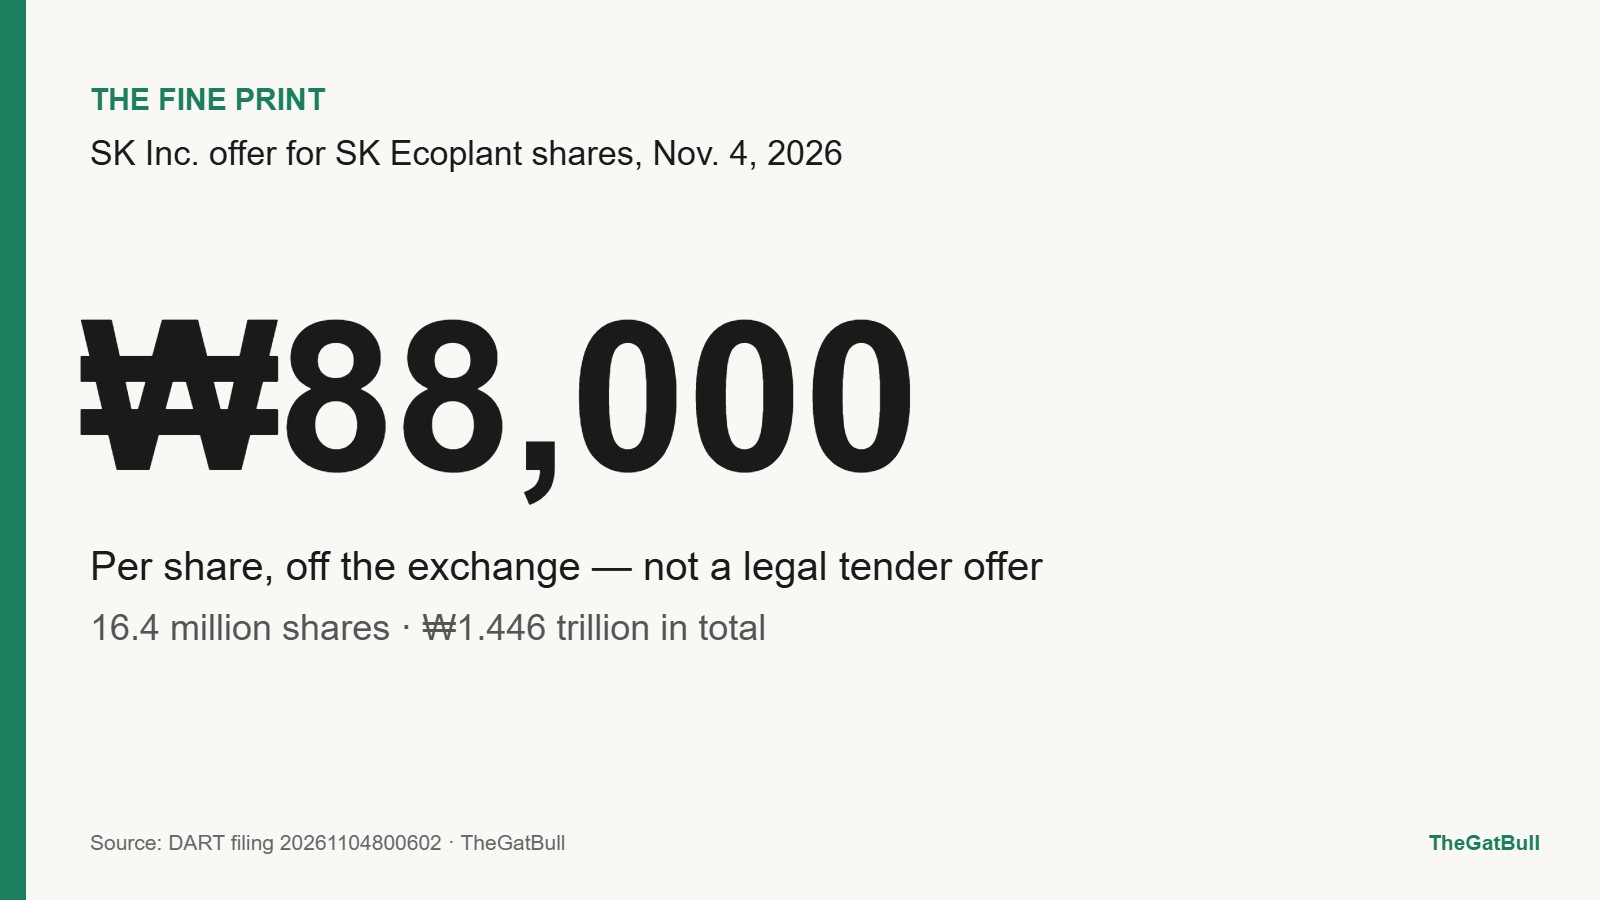
TL;DR — For anyone who saw “SK Ecoplant tender offer” in the news. On Nov. 4, SK Inc. said it will buy all the remaining shares it does not already own in its unlisted subsidiary SK Ecoplant, about 25% of the company, at ₩88,000 each (about $65 at ₩1,347.1 per dollar, Nov. 9), for ₩1.446 trillion in total. English reports called it a tender offer; the Korean filing says the shares are not covered by Korea’s tender-offer law, and that SK will only follow the tender-offer procedure voluntarily.
I’m Mr. Gat, and this is TheGatBull.
Not financial advice.
Dates and times are Seoul time (KST) unless marked ET; in November, ET is 14 hours behind Seoul. Stock and index prices are KRX (Korea Exchange) regular-session closes (3:30 p.m. Seoul). Dollar conversions are for scale only, at the Nov. 9 Seoul 3:30 p.m. rate of ₩1,347.1 per dollar.
SK Inc. (KRX: 034730), the holding company of Korea’s SK Group, filed on Nov. 4 that it will buy 16,434,638 common shares of SK Ecoplant at ₩88,000 each, ₩1.446 trillion (about $1.07 billion) in all, outside any exchange. It then plans to pay cash for any shares still outstanding and own 100% of the company. English headlines called this a tender offer. The filing itself says SK Ecoplant is unlisted, so its shares are not subject to the tender-offer rules in Article 133 of Korea’s Capital Markets Act.
Your Door — what this means for you.
- SK Ecoplant shares in a Korean brokerage account: the first round closes Thursday, Nov. 12, with payment on Nov. 13, through NH Investment & Securities (online or at a branch). If you do not sell, SK has already announced a later step that pays cash for remaining shares.
- SK Inc. or EWY: SK Inc. is 0.69% of EWY (iShares, as of Oct. 16) and SK Ecoplant is not in the fund at all, so this filing does not change what EWY holds and its effect on the fund is small. The number to watch is the ₩1.446 trillion of cash SK Inc. is spending.
SK Inc.’s Nov. 4 filings, in one table
Two filings went to DART, Korea’s electronic disclosure system (the counterpart of the SEC’s EDGAR), on the same day: a voluntary disclosure describing the purchase, and a fair-trade-law notice of a share purchase from affiliated parties. Because both cover one deal, we read them as one event.
| Item | What the filing says (filed) |
|---|---|
| Filings | Voluntary disclosure 20261104800602 · share purchase notice 20261104000339 · board approval Nov. 4 (all five outside directors present) |
| Shares and terms | All 16,434,638 remaining SK Ecoplant common shares (about 25% of shares outstanding); SK will buy every share tendered, regardless of how many holders respond, and pay in cash |
| Price and total | ₩88,000 per share; ₩1,446,248,144,000 in total; after purchase SK would hold 63,135,799 shares, or 96.2% |
| Schedule | Round 1: Nov. 5–12, payment Nov. 13 · Round 2: Nov. 13–24, payment Nov. 25 · securities transaction tax withheld |
The filing says the tender-offer law does not apply
The wording is careful:
- Legal status (filed). SK Ecoplant “is an unlisted company,” and its common shares “are not securities subject to a tender offer under Article 133 of the Capital Markets Act.” SK says it will therefore run an off-exchange purchase (shares bought directly from holders through a broker, without trading on a stock market) that “follows the tender-offer procedure as far as possible,” to give minority shareholders a fair chance to sell. (Our translation.)
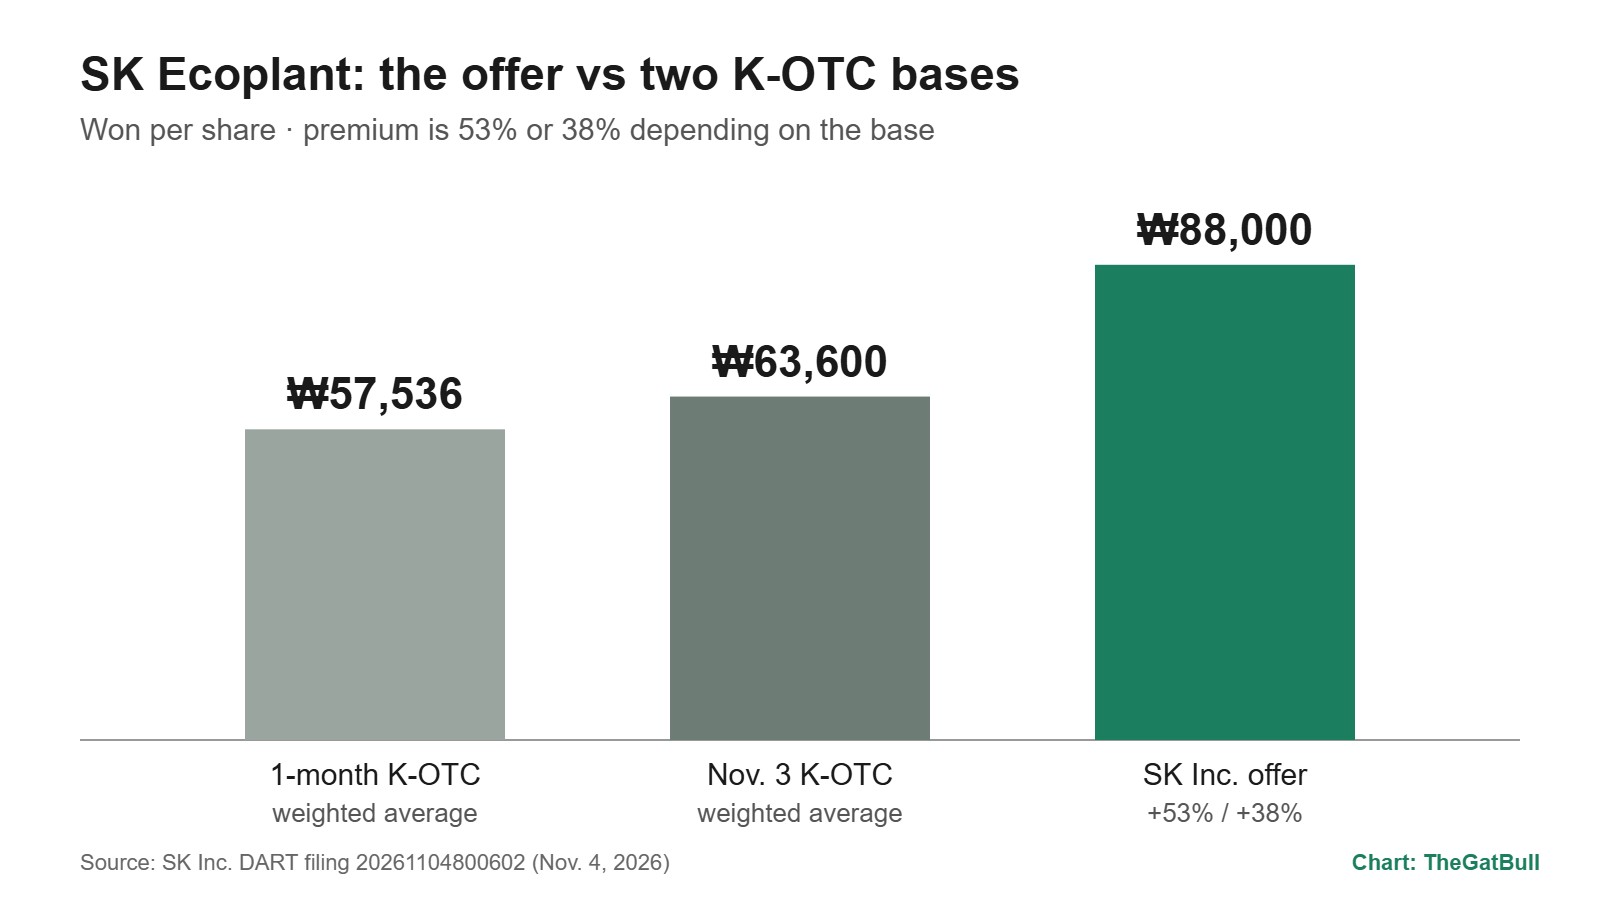
- How the price was set (filed). ₩88,000 is about 53% above the one-month volume-weighted average (the average trade price, weighted by how many shares changed hands) of ₩57,536 on K-OTC, Korea’s over-the-counter market for unlisted shares run by the Korea Financial Investment Association, and about 38% above the Nov. 3 K-OTC average of ₩63,600.
- Purpose (filed). Give shareholders a way to cash out, then make SK Ecoplant a wholly owned subsidiary through a comprehensive share exchange paid in cash (a Korean procedure, similar in effect to a cash-out merger, that moves all remaining shares to the parent), for “responsible management” and efficiency.
- SK’s current stake (our calculation). Subtract the shares on offer from the post-purchase total and SK holds 46,701,161 shares today, about 71.2%. That matches the 71.2% the Korea Herald reported, which it tied to SK’s April purchase of financial investors’ shares for about ₩400 billion (press-reported). The remaining 3.8% or so appears to be treasury stock (shares the company holds in itself); the filing gives no number, so that is not confirmed.
Under the Gat. On Nov. 4, English headlines said “tender offer.” Read that and you may expect the U.S.-style package: a filed offer document, limits on withdrawal, a regulator watching. For holders of the 16.4 million SK Ecoplant shares on offer, Article 133 does not apply; what they have is SK’s written promise in its Nov. 4 filing to follow the procedure. That promise is on the record, which is why the Korean original is worth reading.
The English headlines said “tender offer”
Here is how two English-language outlets put it on the day.
- The Korea Herald (Nov. 4, 5:49 p.m. KST; 3:49 a.m. ET): “SK Inc. scraps SK ecoplant IPO plan, seeks full ownership.” The article says SK “would launch a tender offer” and gives only the 53% premium.
- The Seoul Economic Daily’s English edition (Nov. 4): “SK Inc. to Buy Out SK Ecoplant Minority Stake for 1.45 Trillion Won.” “Buy out” fits the filing.
The headlines differ from the filing in two ways. First, “tender offer” reads as a legal tender offer; the filing says it is not one. Second, the filing gives two premiums, 53% and 38%, and the English report carried only the larger one. Many Korean-language reports also used the word for tender offer, so this looks less like a translation error than an industry habit carried into English. That is our interpretation.
The 53% and 38% premiums use different base dates
On Nov. 3, the day before the announcement, the K-OTC price of ₩63,600 was already 10.5% above the one-month average of ₩57,536 (our calculation: 63,600 ÷ 57,536 − 1). Pick the month and the premium is 53%; pick the last day and it is 38%. A gap of about 15 percentage points comes from the choice of base date alone.
- Implied equity value (our calculation). ₩88,000 times roughly 65.6 million shares is about ₩5.78 trillion (about $4.29 billion). This is not a company figure; we backed out total shares from “63,135,799 shares = 96.2%.”
- SK Inc.’s shares. SK Inc. closed at ₩518,000 on Nov. 4, ₩482,500 on Nov. 5 (down 6.85%), and ₩448,000 on Nov. 9. The KOSPI fell 5.28% to 5,383.80 on Nov. 5 too. The two moves happened on the same day; whether the filing caused SK’s drop is not confirmed. (Yahoo Finance chart data; vendor data rather than exchange-published figures.)
Unlisted subsidiaries sit outside Korea’s tender-offer rules
To buy out minority holders of a listed subsidiary in Korea, a parent faces the tender-offer rules: an offer statement, a set period, limits on withdrawal. An unlisted subsidiary has none of that. In its filing, SK fills that gap itself, with a voluntary disclosure saying it will follow the procedure anyway.
The public price reference here is K-OTC, a thinly traded market, so the premium a company quotes can swing with the base date it chooses, as 53% versus 38% shows.
The second step, the cash-paying share exchange, is the tool that moves out shareholders who do not sell. Two points are open: whether dissenting shareholders will get appraisal rights (the right to demand the company buy their shares at a fair price) at that stage under Korea’s Commercial Act, and whether SK will use a simplified procedure once it passes 90%. SK has not disclosed either; we will not know until a follow-up filing.
This is the second case from the same holding company in about ten days. SK bought out minority holders of its listed unit SK Signet for ₩8,200 a share in cash and then said it would sell the business (our breakdown). This time SK says it wants to keep the company. In both cases it paid cash to reach 100% ownership. That is a pattern in two filings from one group; we have not checked whether it holds across the Korean market. The Korea Herald cited the government’s stance against dual listing (listing a subsidiary separately while its parent is already listed) as background to the IPO withdrawal (press-reported). We looked at how that “holding-company discount” works in our SK Square piece.
Three dates to watch: Nov. 12, Nov. 24 and the share-exchange filing
- Nov. 12 (round 1 closes) and Nov. 13 (payment): the results filing shows how many shares minority holders actually sold.
- Nov. 24 (round 2 closes) and Nov. 25 (payment): how close SK’s final stake gets to 96.2%.
- The share-exchange filing: whether the exchange price matches ₩88,000, and the price offered to dissenting holders.
Risk: because this is not a legal tender offer, the statutory procedure for any change of terms or delay is not clear; holders would learn of changes only through SK’s voluntary disclosures.
How U.S. investors can reach SK, and the American comparison
The two companies are reached in different ways.
- Access. SK Ecoplant is unlisted, absent from EWY, and has no U.S. listing; it is reachable only through a Korean brokerage account (K-OTC). SK Inc. trades on the Korea Exchange (034730); we did not confirm any U.S. ADR. It is 0.69% of EWY (Oct. 16). From a U.S. account, the route is a broker with Korea Exchange access — see how U.S. investors buy Korean stocks.
- U.S. comparison. When a U.S. parent buys out the minority of a listed subsidiary, it files a Schedule TO (the tender-offer document) and a Schedule 13E-3 (fairness disclosure for going-private deals) with the SEC. Not a perfect parallel: SK Ecoplant is unlisted, so even in the U.S. it would likely not have fallen under these filing duties for SEC-registered companies. In both countries “tender offer” implies a set of required legal filings, and this deal does not carry them.
The bottom line
When a Korean parent cleans up the minority of an unlisted subsidiary, the tender-offer law does not reach it. SK filled that gap with a sentence in its filing promising to follow the procedure. The price reference is a thin K-OTC market, so the premium is 53% or 38% depending on the date. The headline word “tender offer” is fair as industry shorthand, but it invites expectations of the statutory protection that the filing says does not apply. That last point is our interpretation.
The Seoul Seven · how this piece was checked: ✓ Korean original · ✓ Dated sources · ✓ Seoul & New York time · ✓ Beyond EWY · ✓ U.S. anchor · ✓ What to watch · ✓ Corrections kept · what these mean
— Mr. Gat. Stay bullish. (Meaning: read Korean filings to the end. Not a call to buy or sell.)
Related reading: Why Is SK Buying Out SK Signet? To Sell It, It Says. · SK Square and the holding-company discount · How U.S. investors buy Korean stocks
FAQ
What did SK Inc. disclose on Nov. 4, 2026?
That it will buy all 16,434,638 remaining SK Ecoplant shares (about 25%) off the exchange at ₩88,000 each, ₩1.446 trillion in total, then use a cash-paying share exchange to own 100% of the company (DART 20261104800602).
Is SK Inc.’s SK Ecoplant offer a tender offer?
Reports in English and Korean called it one, but the filing says SK Ecoplant’s shares are not subject to the tender-offer rules in Article 133 of the Capital Markets Act. SK describes it as an off-exchange purchase that follows the tender-offer procedure voluntarily.
Is SK Ecoplant listed, or in EWY?
No to both. It is unlisted and trades on K-OTC. Its parent, SK Inc., is listed on the Korea Exchange and is 0.69% of EWY (as of Oct. 16, 2026).
Why do reports say 53% while the filing also says 38%?
Different base prices. The premium is 53% over the one-month K-OTC average of ₩57,536 and 38% over the Nov. 3 K-OTC price of ₩63,600.
Sources
- SK Inc. filings on DART, Nov. 4, 2026: voluntary disclosure 20261104800602 · share purchase from affiliated parties 20261104000339.
- The Korea Herald, “SK Inc. scraps SK ecoplant IPO plan, seeks full ownership,” Nov. 4, 2026, 5:49 p.m. KST (press: April purchase from financial investors, 71.2% stake, external valuation).
- Seoul Economic Daily (English), “SK Inc. to Buy Out SK Ecoplant Minority Stake for 1.45 Trillion Won,” Nov. 4, 2026.
- Prices: Yahoo Finance chart data (034730.KS, ^KS11; vendor data, not exchange-published figures).
- iShares MSCI South Korea ETF (EWY) holdings, as of Oct. 16, 2026.
- Won-dollar rate at the Seoul 3:30 p.m. close, Nov. 9: Asia Economy (press), checked against the previous day’s close.
How sure are we?
| Item | Confidence |
|---|---|
| Share count, price, total, schedule, premiums, legal status, next step | ✅ Company filings on DART |
| SK’s current 71.2% stake, implied equity value, dollar conversions | Our calculation from filed figures |
| April purchase from financial investors | ⚠️ Press-reported (Korea Herald) |
| Closing prices | Vendor data (Yahoo), KRX regular-session close |
| EWY weight | ✅ iShares holdings file, as of Oct. 16, 2026 |
| Treasury shares, appraisal rights at the exchange stage, cause of SK’s Nov. 5 drop | Not confirmed |
Not financial advice. TheGatBull is an independent publication; nothing here is a recommendation to buy or sell any security.
 Written by Mr.Gat — TheGatBull
Korean market coverage from a Seoul-metro-based operator with 15 years of personal investing experience, who reads the filings in the original language. Every price on this site is the KRX regular-session close (15:30 Seoul); every figure states whether it came from a primary filing, the press, or our own calculation. Drafts are AI-assisted, then verified against the original Korean documents and edited by a human before publishing.
Found an error? Tell us — corrections get priority. How we work →